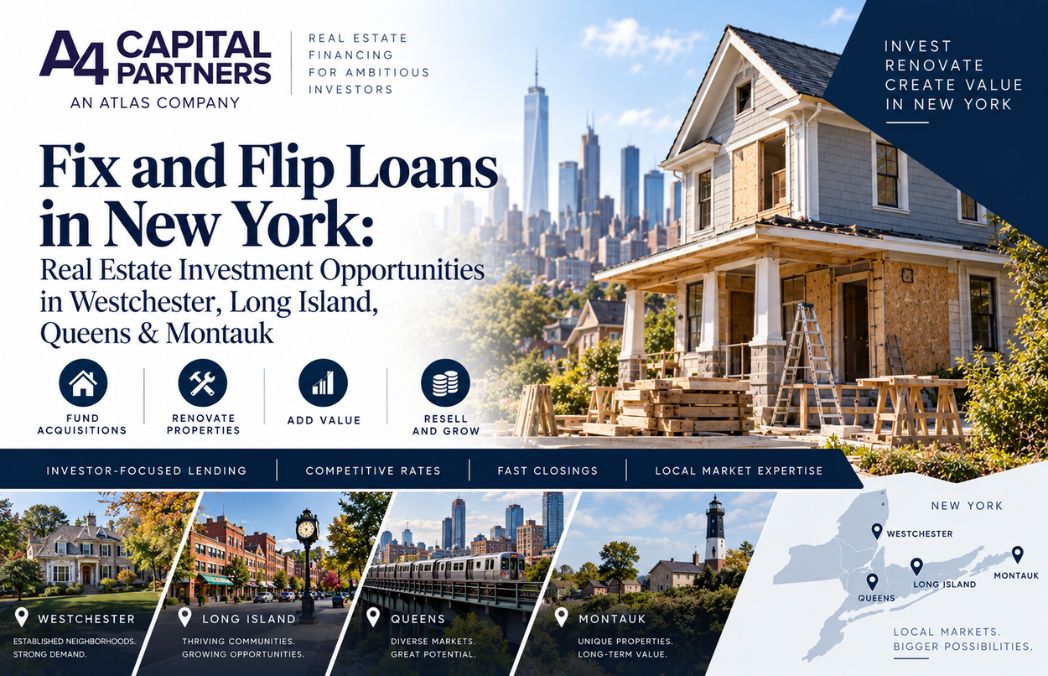
Fix and Flip Loans in New York: Real Estate Investment Opportunities in Westchester, Long Island, Queens & Montauk
Blogs·Sep 14, 2026
In June 2026, the median single-family home in Nassau County sold for $875,000 and buyers were still paying above the original asking price. That same quarter, closed sales in Queens fell 8.4% year over year and homes sat roughly 65 days before going under contract. Two markets, about fifteen miles apart, moving in opposite directions.
That gap is the whole argument for treating New York as a collection of markets rather than one. An investor who learns to read Nassau County comps will misprice a Montauk oceanfront renovation. A Queens operator who knows how to work a two-family in Astoria has almost nothing transferable to a Scarsdale colonial with a $30,000 tax bill attached to it.
This guide looks at four of those markets in detail: Westchester County, Long Island (Nassau and Suffolk), Queens, and Montauk. For each one, what the housing stock actually looks like, where value-add opportunities tend to sit, what buyers there expect from a renovated home, and the local costs that quietly decide whether a project pencils. Financing matters, and fix and flip loans New York investors use can fund both the purchase and the rehab. But the property has to make sense first.
New York’s Diverse Real Estate Markets for Fix and Flip Investors
New York State contains some of the most expensive suburban housing in the country, a dense borough market where two-family homes are the standard investment vehicle, and a seasonal resort market where a renovated house can sit for four months waiting on the right buyer. Averaging them together produces a number that describes nowhere.
The differences run deeper than price. Westchester and Nassau are built out, with housing stock dominated by pre-1970 colonials, capes, and split-levels on established lots, in school districts that drive buyer behavior more than almost any other variable. Queens is a borough of attached and semi-detached houses, two- and three-family buildings, and co-op and condo stock, where renovation work runs through the NYC Department of Buildings and a property’s certificate of occupancy can make or break a deal. Suffolk County stretches roughly 85 miles east and behaves like four or five markets stacked end to end, from dense Babylon and Islip neighborhoods to North Fork farmland to the East End resort towns. Montauk sits at the far end of that line, in the Town of East Hampton, operating on second-home money and a summer selling season.
Renovation expectations vary just as much. In Westchester’s upper price tiers, buyers want finished, and they want it done at a level that matches a $1 million-plus purchase. In parts of Queens, a clean, code-compliant two-family with updated mechanicals and a legal layout will find a buyer faster than a high-design kitchen. Montauk buyers are comparing against new construction and gut renovations with premium finishes.
Comparable sales are the only reliable guide, and they operate at the neighborhood and school-district level, not the county level. Two Westchester houses six minutes apart can sit in different districts and carry a $150,000 spread in value. That’s the level at which flips are won or lost.
Fix and Flip Loans in Westchester County, New York
Westchester is a high-price, low-inventory market with a large stock of aging homes and buyers who reward finished work. That combination creates real renovation opportunity, and it also sets a high floor on acquisition cost.
What the Westchester market looks like
The numbers have been moving up for several years. In February 2026, the Hudson Gateway Association of Realtors reported a median single-family sale price in Westchester of $1,025,500, up 19.8% year over year, with only 1.3 months of single-family inventory and most homes selling in about a month. Houlihan Lawrence’s Q1 2026 report showed single-family sales volume down 16% year over year while the average sale price climbed 11% to roughly $1.3 million. By the second quarter, the firm’s Q2 report described a market gradually becoming more balanced, with more selection for buyers. CEO Liz Nunan noted that buyers had become more selective but stayed ready to act when well-priced, move-in-ready homes came to market.
That last observation is the one flippers should underline. In a market where most listings are older houses in original condition, a properly finished renovation is a differentiated product.
Where value-add opportunity tends to sit
Most of Westchester’s housing stock predates 1970, which means the common project profile is modernization rather than repositioning: dated kitchens and baths, original electrical service, oil heat, aging roofs, and floor plans that close the kitchen off from the living space. Buyers in this county consistently pay for open main floors, updated systems, and finished outdoor space.
The county is not one market, though. The river towns, Yonkers, Mount Vernon, and parts of New Rochelle offer lower entry prices with tighter resale ceilings. White Plains carries a mix of multifamily, co-op, and single-family stock near transit. Scarsdale, Bronxville, and Rye operate in a different price universe entirely, where the Q2 2026 luxury report showed sales above $2 million climbing more than 16% and the top quarterly sale hitting $10 million in Rye. Renovation standards, contractor costs, and buyer tolerance for compromise differ sharply across those tiers.
Local considerations that change the math
Property taxes are the big one. ATTOM’s national property tax analysis has repeatedly ranked Westchester among the highest average single-family tax bills in the United States, with local estimates for the county’s median bill running well into five figures. On a nine-month hold, taxes alone can absorb a meaningful share of projected margin, and the bill varies enormously by municipality and school district on similarly priced homes.
There’s a pricing threshold worth knowing too. Outside New York City, New York State’s 1% “mansion tax” applies to residential sales of $1 million or more and is paid by the buyer on the entire purchase price, not just the amount above the line. With the county median sitting right at that mark, a Westchester resale priced at $1,000,000 costs the buyer $10,000 more than one at $999,000. That threshold shapes how renovated homes get positioned.
Investors working suitable Westchester properties often fund acquisition and renovation through short-term private financing rather than conventional loans, which rarely accommodate a house that isn’t currently habitable. The structure is straightforward, and A4CP’s existing New York financing content covers it.
Fix and Flip Loans in Long Island, New York
Long Island isn’t a market. It’s two counties with roughly 2.8 million residents, and treating them as a unit is the most common analytical mistake investors make here.
What Nassau and Suffolk do share, right now, is scarcity. OneKey MLS June 2026 data put the median single-family price at $875,000 in Nassau and a record $750,000 in Suffolk, with both counties reporting median sale-to-original-list-price ratios above 101% and combined single-family inventory down roughly 9.1% year over year. Homes that are priced correctly and presented well are still clearing at or above ask. That’s a favorable backdrop for a renovated product, and a difficult one for acquisition.
Fix and Flip Opportunities in Nassau County
Nassau is dense, built out, and overwhelmingly postwar. The county’s suburban expansion happened in a compressed window after 1945, which left behind an enormous inventory of capes, ranches, splits, and expanded Levitt-era houses now 70 to 80 years old. Many have been added onto once or twice, sometimes without permits.
That creates a specific opportunity: houses with good bones and bad layouts. Dormer additions, kitchen reconfigurations, primary suite conversions, and mechanical updates tend to return well because the surrounding comps support a finished price and the buyer pool skews toward families who want to move in and be done.
Two things to check before writing an offer. First, permit history. Unpermitted additions and finished basements are common in Nassau, and legalizing them or removing them is a real line item. Second, the tax bill. Nassau’s assessment history has been contentious, and single-family tax bills commonly run into five figures, which affects both your carry and your buyer’s monthly payment. The pricing ceiling in a given hamlet is set by comps within that school district, and Nassau’s districts are small and numerous.
Fix and Flip Opportunities in Suffolk County
Suffolk is the more geographically varied market and, for a lot of investors, the more accessible entry point. Western Suffolk towns like Babylon, Islip, and Huntington function as a continuation of the Nassau suburban pattern at somewhat lower price points. Move east and the character changes: larger lots, more 1960s and 1970s construction, seasonal and waterfront pockets, and stretches where the buyer pool thins out quickly.
Resale timing deserves more respect here than it usually gets. Suffolk holding periods tend to run longer than Nassau’s, particularly east of Riverhead, and a renovation finished in October may be waiting on spring.
The regulation investors most often miss is wastewater. Under Article 6 of the Suffolk County Sanitary Code, new construction and major reconstruction trigger a requirement for innovative and alternative onsite wastewater treatment systems, the nitrogen-reducing units known as I/A OWTS. “Major reconstruction” is generally read as work costing 50% or more of the property’s market value, and adding bedrooms can trigger it as well. A gut renovation on a cesspool property can therefore carry a system requirement that commonly runs $15,000 to $30,000 installed, far more than a conventional septic. County and state grant programs exist, but eligibility rules apply and they were not written with investors in mind. Confirm system type and permit status during due diligence, not after demolition.
Investors acquiring value-add property in either county frequently use short-term rehab financing to cover purchase and construction in a single structure. For loan mechanics, draw schedules, and underwriting criteria, A4CP’s guide to fix and flip loans in New York covers the detail.
Fix and Flip Loans in Queens, New York
Queens is the outlier in this group right now, and that’s exactly why it deserves a close look.
While Long Island inventory tightened through 2026, Queens softened. OneKey MLS reported a Q2 2026 median price of $664,000 in Queens, up 2% year over year but down 3.1% from the prior quarter, with closed sales off 8.4% year over year and inventory rising through the first half. Redfin data for Queens County showed homes taking about 65 days to sell in spring 2026, up from 56 days a year earlier. Slower absorption isn’t automatically bad for an investor. It usually means more negotiating room at acquisition. It also means a longer, more expensive hold, and that tradeoff has to be underwritten honestly.
Queens Real Estate Opportunities for Fix and Flip Investors
The borough’s defining feature for investors is its two- and three-family housing stock. In Ozone Park, Richmond Hill, Woodhaven, and parts of Jamaica, legal two-families draw sustained demand from owner-occupant buyers using FHA financing, who live in one unit and rent the other. That buyer pool is deep, rate-sensitive, and very specific about what it wants: legal units, separate utilities, a clean certificate of occupancy, and functional mechanicals.
Different submarkets, different products. Astoria and Long Island City lean toward condo and small multifamily repositioning and attract a younger buyer paying for finish quality and proximity to Manhattan. Forest Hills and Bayside carry more prewar detached and semi-detached single-family stock, where the project is usually a full modernization of an older colonial or Tudor. Jackson Heights is co-op-dominated, which is a fundamentally different transaction with board approval and building rules that can complicate a resale timeline.
What Queens Investors Should Consider Before Buying
Three items sit above the rest.
Certificate of occupancy and legal use. A house marketed as a two-family that’s legally a one-family with a finished basement is a different asset and a different resale price. Pull the CO and the DOB records before you’re under contract.
Permit reality. Work in Queens runs through NYC DOB. Filings, inspections, and sign-offs take longer than in Nassau or Suffolk, and that time is holding cost. Build it into the schedule rather than discovering it in month five.
Seller-side transfer taxes at exit. New York City’s Real Property Transfer Tax is customarily paid by the seller at 1.425% on residential sales above $500,000, plus the 0.4% New York State transfer tax, for a combined burden around 1.825%. On a $900,000 Queens resale, that’s roughly $16,400 off the top before broker commission. This line item doesn’t exist in Nassau or Westchester, and investors who move between the two markets routinely forget it.
Fix and flip financing works the same way in Queens as anywhere else in the state. The underwriting question is whether the property and the exit support the structure.
Fix and Flip Loans in Montauk, New York
Montauk is a hamlet within the Town of East Hampton, in Suffolk County, at the eastern tip of Long Island’s South Fork. Not a county, not a town, and not comparable to any other market on this list.
Montauk Real Estate Investment Opportunities
Prices here are high and the perception that Montauk is the affordable end of the East End is about fifteen years out of date. Redfin data covering the Montauk area put the median sale price near $1.6 million for the three months ending June 2026, up 8% year over year. The broader Hamptons market set a record in the fourth quarter of 2025, with Douglas Elliman and Miller Samuel reporting a median of $2.34 million, up 34%, driven largely by a shift in sales mix toward the high end while lower and middle segments stayed under pressure from financing costs.
The housing stock includes a substantial number of modest mid-century beach houses and 1970s contemporaries on valuable land. Many were built as seasonal cottages and never fully modernized. That’s where the value-add case lives: the improvement opportunity is often a gut renovation or a substantial expansion that repositions a dated house to compete with new construction.
Buyers are mostly second-home purchasers, and many pay cash. They compare a renovated house against turnkey inventory and new builds, which sets a high bar on finish quality. A partial renovation in Montauk tends to satisfy nobody.
What Investors Should Consider Before Flipping in Montauk
A high sale price does not make a good flip. The costs here are structurally different, and four of them matter most.
Time on market. Redfin showed Montauk-area homes averaging 104 days to sell in mid-2026, up from 80 a year earlier, and other trackers put average days on market above 110 with sale-to-list ratios below 95%. Nationally, ATTOM’s Q1 2026 report found the median flip took 165 days from purchase to resale. In Montauk, the marketing period alone can consume a large part of that budget.
Seasonality. Demand concentrates around the summer season. A project finishing in September is often really finishing in April, and nine months of carry on a $1.8 million asset is not a rounding error.
The East End transfer tax. Buyers in the Town of East Hampton pay a 2.5% Peconic Bay Region transfer tax, 2% to the Community Preservation Fund plus a 0.5% Community Housing Fund surcharge added in April 2023. The first $400,000 of an improved residential parcel is exempt where consideration is $2 million or less, and the exemption is lost above $2 million. On a $1.9 million acquisition that’s $37,500 at closing. Cross $2 million and the same tax jumps to more than $50,000. Verify the current schedule and exemptions with the town and your title company before you model the deal.
Construction cost and capacity. East End labor is expensive, contractor calendars fill early, and Suffolk’s Article 6 wastewater requirements frequently apply to the scale of renovation Montauk properties call for.
Fix and flip financing can support this kind of project, but the underwriting conversation is different from a $600,000 Suffolk cape. Longer timelines and larger budgets need to be reflected in the loan structure from the start.
Comparing Fix and Flip Investment Opportunities in New York
No market on this list is better than the others. They suit different capital positions, different renovation capabilities, and different tolerances for holding risk.
| Market | Real estate characteristics | Potential investor opportunities | Key considerations |
|---|---|---|---|
| Westchester County | High-price suburban market, county median single-family above $1M in early 2026, mostly pre-1970 housing, very tight inventory, sharp price tiers by school district | Modernizing dated colonials, capes and splits; open-plan reconfigurations; systems and exterior updates in mid-tier cities and river towns | Among the highest property tax bills in the US; wide value spread between adjacent districts; 1% state mansion tax at the $1M resale threshold |
| Long Island (Nassau) | Dense postwar suburbia, June 2026 single-family median $875K, sale-to-list above 101%, very limited supply | Layout-constrained postwar homes; dormer and addition projects; primary suite conversions | Unpermitted additions are common; high tax bills affect buyer affordability; small school districts set narrow comp sets |
| Long Island (Suffolk) | Geographically diverse, June 2026 single-family median $750K (record), western towns suburban, eastern towns seasonal | Broader entry-price range; 1960s–70s stock needing modernization; waterfront and near-water pockets | Article 6 I/A OWTS triggers on major reconstruction; longer absorption east of Riverhead; seasonal listing timing |
| Queens | Urban borough, Q2 2026 median $664K, softening sales and rising inventory, DOM lengthening toward 65 days | Legal two- and three-families for FHA owner-occupant buyers; prewar single-family modernization; condo repositioning in western Queens | Certificate of occupancy and legal-use verification; NYC DOB permit timelines; ~1.825% seller-paid city and state transfer tax at exit |
| Montauk | Seasonal second-home market in the Town of East Hampton, median near $1.6M mid-2026, DOM above 100 days | Gut renovation of mid-century cottages and dated contemporaries on high-value land | 2.5% Peconic Bay transfer tax with an exemption cliff at $2M; summer-weighted demand; premium finish expectations; East End construction costs |
What Makes a New York Property Worth Considering for a Fix and Flip?
Strip away the market differences and the selection criteria are consistent. The weight each one carries is what changes.
Acquisition price relative to local comps. Not county medians. The last six months of sales within the same school district, block pattern, or building type.
Condition and scope. Cosmetic updates, systems replacement, and structural work are three different risk categories with three different budget error rates. Be honest about which one you’re buying.
Buyer demand for the finished product. Does the neighborhood’s active buyer pool actually want what you plan to build? A high-design open kitchen doesn’t help if the local buyer is an FHA owner-occupant who needs a legal second unit.
Total project cost against realistic resale. Investors generally compare the expected value of the renovated property against the full cost of the project, including acquisition, renovation, financing, taxes, insurance, utilities, and sale costs, to decide whether the deal works. If the spread only exists under optimistic assumptions, it isn’t a spread.
Holding costs and time. Property taxes, insurance, utilities, and interest accrue whether or not the work is moving. In Westchester and Nassau, taxes dominate. In Montauk, time on market does. In Queens, permitting does.
Exit costs specific to the location. Transfer taxes, commission, attorney fees, and any transaction-specific charges vary by market and can shift net proceeds by tens of thousands of dollars.
A defined exit. Sale, refinance into a rental hold, or a fallback if the primary plan stalls. Projects without a second option are the ones that get expensive.
Why Local Market Knowledge Matters for New York Fix and Flips
A flip that works in one part of New York will not automatically work in another. The 2026 data makes the point better than any argument could.
Long Island inventory tightened and sellers cleared above ask. Queens sales fell and days on market stretched. Those two markets are adjacent, share a border, and moved in opposite directions in the same six months. An acquisition model calibrated to Nassau’s speed would have overstated a Queens exit timeline by weeks.
Nassau and Suffolk diverge too. Nassau’s constraint is supply and its risk is acquisition price. Suffolk’s variability is geographic, and its distinctive cost exposure is wastewater compliance under a county code that Nassau investors never encounter.
Long Island versus Montauk is the widest gap of all. A renovated Suffolk cape sells to a local buyer, year-round, in a competitive market. A renovated Montauk house sells to a discretionary second-home buyer during a concentrated season, at a price point where a 2.5% transfer tax and a four-month marketing period are normal.
And Queens versus Westchester barely share a vocabulary. One is a city market with DOB filings, certificates of occupancy, and seller-paid transfer taxes. The other is a suburban market where school district boundaries and property tax bills decide value, and where the same renovation budget buys a different level of finish.
The practical takeaway: build comps, contractor relationships, and cost assumptions market by market. Reusing them across county lines is how good projects turn into mediocre ones.
Financing a Fix and Flip Property in New York
Once a property clears your analysis, financing becomes an execution question. Conventional mortgage products generally aren’t built for houses that need work, and the timelines rarely match a competitive offer.
Short-term fix and flip financing addresses three things: funding the acquisition, funding the renovation budget, and doing both on a schedule that lets an investor compete with cash buyers. Structures vary by lender, by property type, and by the borrower’s experience, so terms aren’t uniform across the market.
What investors should have ready when they approach a lender:
- A detailed renovation budget and scope of work from a licensed contractor
- A realistic view of the property’s value after renovation, supported by local comparable sales
- A project timeline that reflects local permitting and seasonality, not a best case
- Total cost of capital, including interest and fees, across the full expected hold
- A defined exit, plus a fallback if the primary one stalls
For loan structures, draw schedules, underwriting criteria, and the terminology behind them, A4CP’s guide to fix and flip loans in New York covers that ground in depth. This article is about picking the right property first.
Fix and Flip Loans for New York Real Estate Investors
A4 Capital Partners works with real estate investors across New York, including New York City and statewide markets such as Long Island, Westchester, Albany, Buffalo, and Rochester. The firm provides asset-based financing for single-family renovation projects, condo and townhouse flips, small multifamily repositioning, distressed acquisitions, and value-add residential investments.
Loan amounts are determined by purchase price, projected after-repair value, renovation scope, and leverage structure, and approved rehab budgets are funded through draws tied to verified construction milestones. Financing structures vary by project and borrower, and all lending is subject to underwriting and credit approval. For current program details, contact A4CP directly.
The reason this matters for a market guide: the properties described above have very different capital requirements. A Queens two-family, a Nassau dormer project, and a Montauk gut renovation need different loan sizes, timelines, and draw structures. Matching the financing to the project is part of the underwriting, not an afterthought.
Learn more about fix and flip loans in New York and how financing is structured for different project types.
Frequently Asked Questions
Where can investors find fix and flip opportunities in New York?
Opportunities exist across the state, but they look different in each market. Westchester and Nassau offer large inventories of aging postwar and prewar homes needing modernization. Suffolk provides a wider entry-price range. Queens centers on two- and three-family properties and older single-family stock. Montauk and the East End involve high-value seasonal renovations. Each requires its own comp research and cost assumptions.
Are fix and flip loans available in Westchester County?
Yes. Lenders that finance New York investment property generally cover Westchester County, and A4CP lists Westchester among its New York lending markets. Approval depends on the property, the renovation scope, the projected after-repair value, and the borrower’s plan rather than on the county itself. Given Westchester’s high acquisition prices and property tax bills, lenders pay close attention to holding cost assumptions.
Can investors use fix and flip loans for properties on Long Island?
Yes, in both Nassau and Suffolk counties. Short-term rehab financing is commonly used on Long Island because so much of the housing stock is 60 to 80 years old and doesn’t meet conventional lending condition standards. Suffolk projects deserve extra diligence on wastewater compliance, since major reconstruction can trigger an I/A OWTS requirement under the county sanitary code.
Are fix and flip loans available for Queens investment properties?
Yes. Queens projects are financed regularly, including single-family homes, legal two- and three-family properties, condos, and townhouses. Lenders will want to see the certificate of occupancy and confirm legal use, particularly on multifamily properties where the marketed configuration doesn’t always match the permitted one. NYC permitting timelines should be reflected in the project schedule.
Can investors get fix and flip loans for properties in Montauk?
Yes, though Montauk projects are underwritten differently. The larger loan sizes, premium finish expectations, seasonal selling window, and longer days on market all affect the structure. Investors should account for the 2.5% Peconic Bay Region transfer tax paid at acquisition in the Town of East Hampton, along with East End construction costs and potential wastewater system requirements.
What should investors consider when flipping a property in Westchester?
Start with the school district, because it drives comps more than almost anything else. Then the tax bill, which in Westchester can materially affect both carrying cost and your buyer’s affordability. Renovation scope should match the price tier, since buyers above $1 million expect finished quality. Watch the $1,000,000 resale threshold, where New York State’s 1% mansion tax applies to the buyer.
Is Long Island a good market for fix and flip investing?
Long Island has favorable conditions for finished product, with limited inventory and June 2026 data showing homes selling above original list price in both counties. The challenge is acquisition, since competition for value-add properties is strong and entry prices are high. Whether a specific project works depends on the individual property, the neighborhood comps, and the total cost, not on the market as a whole.
Conclusion
New York isn’t one real estate investment market, and the 2026 data proves it. Nassau and Suffolk tightened while Queens softened. Westchester’s prices climbed on almost no inventory. Montauk kept setting high prices while taking more than a hundred days to sell a house. Four markets, four different sets of buyers, four different cost structures, four different definitions of a finished home.
Investors who do well in New York tend to pick a market, learn its comps and its contractors, and understand the local costs that don’t appear in a generic flip calculator. Renovation opportunity and resale demand both vary block by block, which is why property-level and neighborhood-level analysis beats county-level assumptions every time. Financing is what lets a viable project get executed on a competitive timeline. But the property has to make sense first.
Evaluating a fix-and-flip property in New York? Explore A4CP’s fix and flip loan options for New York investors to learn more about financing your next acquisition and renovation project.