New Construction Loan Rhode Island: Financing Projects Across 5 Key Counties
Blogs·Oct 21, 2026
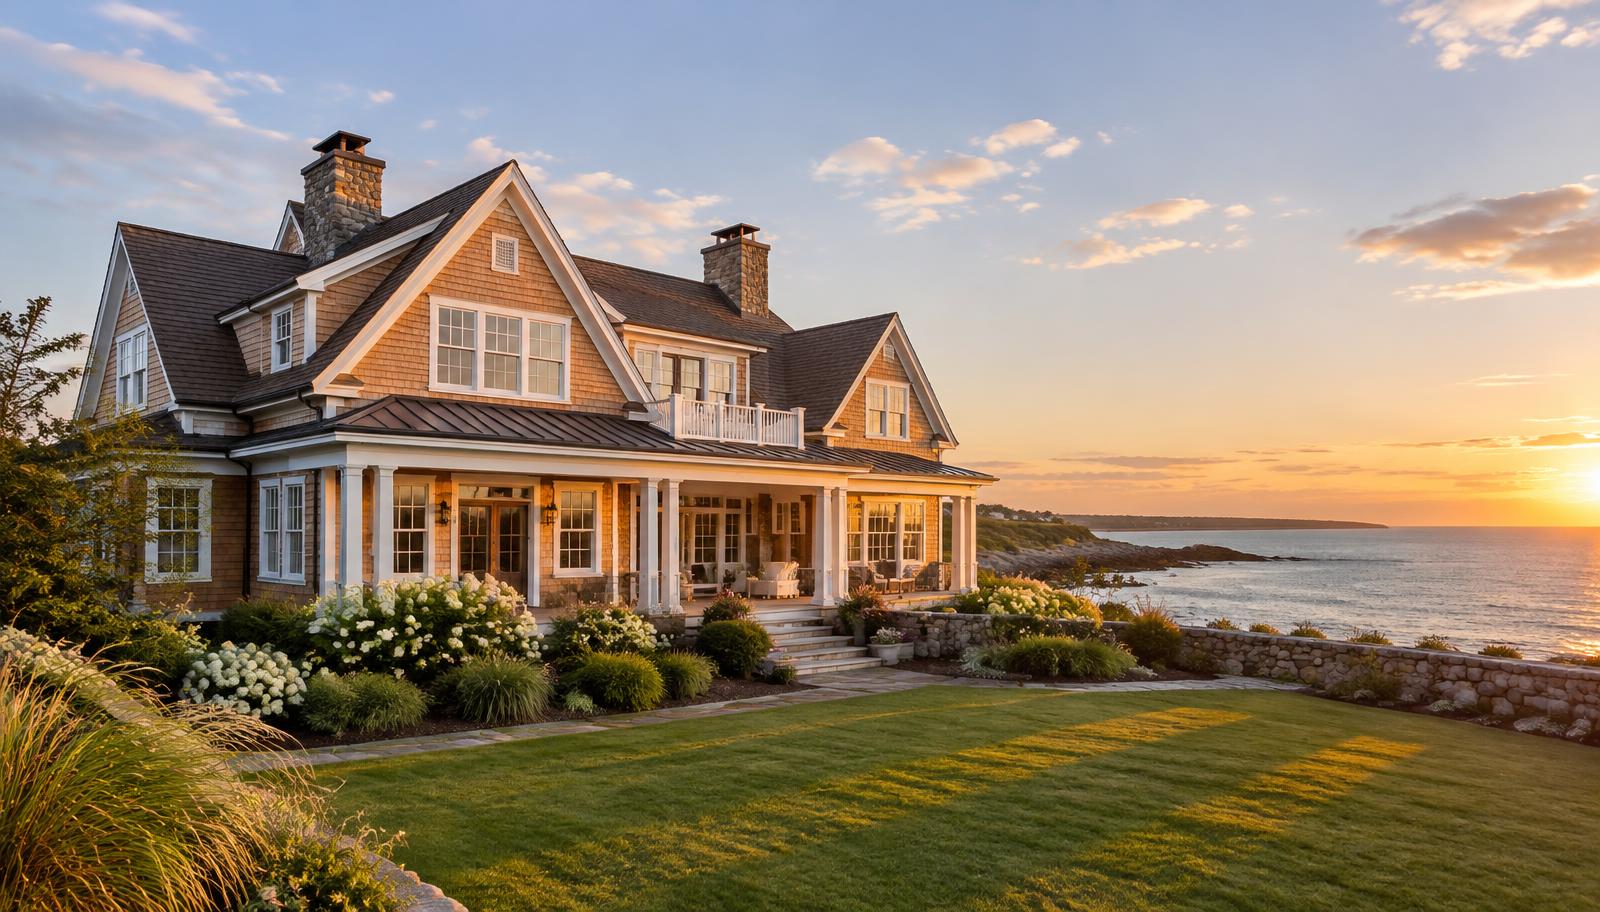
Short answer: a new construction loan in Rhode Island is short-term financing that pays for building a home, usually released in stages as work is completed. Lenders size it around the land cost, an itemized construction budget, the projected completed value, the borrower's equity and a clear plan to repay the loan. How a project is evaluated depends on its location and purpose: a waterfront spec home in Newport County, a shoreline build in Washington County and a suburban rental project in Kent County raise different questions.
This guide explains how construction financing works and what to prepare, organized around five counties: Newport, Washington, Bristol and Providence, with a shorter look at Kent. If you are ready to price a project, see A4's luxury new construction loans in Rhode Island page for current program terms. It is general information, not legal, tax or investment advice.
A4 Capital Partners provides business-purpose financing for builders and real estate investors, for example a spec home built for sale. It does not offer construction mortgages for a home you plan to live in.
What Is a New Luxury Construction Loan in Rhode Island?
A construction loan funds the cost of building a property. A luxury construction loan applies the same structure to high-value homes, where finishes, site work and approvals tend to be larger and more complex.
What a construction loan typically funds
- Hard costs: foundation, framing, systems, finishes and site work.
- Approved soft costs, such as architecture, engineering and permits, when the lender allows them.
- In some structures, part of the land or acquisition cost.
Who uses construction financing
Builders, developers and real estate investors use private construction loans for projects they plan to sell or rent. Homeowners building a primary residence generally need a consumer construction mortgage from a bank or mortgage lender instead.
Land acquisition versus construction-only financing
If you already own the lot, the land is usually treated as part of your equity and the loan funds construction. If you are buying the land, some lenders finance part of the purchase together with the build, while others require you to own the land first. Ask early, because this changes how much cash you need at closing.
How draws work
The construction budget is normally held back and released in draws. After a phase is completed, you submit a draw request, the lender verifies the work, often through an inspection, and funds are advanced for that budget line.
Short-term construction loans versus construction-to-permanent loans
A short-term construction loan is repaid when the project is sold or refinanced. A construction-to-permanent loan converts into a long-term mortgage after completion and is mostly a consumer product for owner-occupants. Product availability varies by lender.
Types of New Luxury Construction Financing Available in Rhode Island
- Ground-up construction financing: building a new home on vacant or cleared land.
- Teardown and rebuild: replacing an existing house with a new one on the same lot.
- Private construction loans: short-term, asset-focused loans from private or balance-sheet lenders, typically faster and more flexible than bank loans but often priced higher.
- Construction-to-permanent financing: offered by some banks for owner-occupied homes. A4 does not offer this product.
- Investment residential construction: spec homes, build-to-rent single-family homes and small residential projects with a defined exit.
A4 Capital Partners focuses on business-purpose luxury new construction loans for spec homes, ground-up investment builds and teardown/rebuild projects.
Newport County: Financing Luxury and Waterfront Construction
Newport County is the leading luxury and coastal market in A4's Rhode Island strategy. Projects here often combine high land values, custom specifications and site conditions that need careful review.
New Construction Loans in Newport, Middletown, Jamestown, Tiverton and Little Compton
For a new construction loan in Newport RI or elsewhere in the county, lenders will look closely at:
- Land basis: what you paid for the lot or teardown, and whether you own it free and clear.
- Budget that matches the finish level: a high-end coastal home needs a detailed, line-item budget, not an estimate per square foot.
- Valuation support: the projected completed value should come from comparable sales of similar new or renovated homes in the same area, not from listing prices.
- Site-specific coastal review: properties near the shoreline may need approvals from the Rhode Island Coastal Resources Management Council (CRMC) in addition to local permits. Flood zone status can affect design, cost and insurance.
- Builder experience: a contractor with a record of comparable high-value projects strengthens the file.
Waterfront construction financing in Rhode Island is not automatic. Lenders evaluate each site, and some coastal or highly custom properties will not fit a given program.
Washington County: Construction Financing for Coastal Homes and Second Properties
Washington County, often called South County, is a shoreline market with a large share of second homes. Investor projects here are frequently planned around the eventual buyer's use of the home.
New Construction Loans in Narragansett, South Kingstown, Westerly and Block Island
- Intended use: A4 finances investment projects. Be clear about whether the home will be sold or held as a rental, and how that fits the lender's rules.
- Permitting: shoreline lots may need state coastal approvals as well as town permits. Know where approvals stand before you apply.
- Site access and logistics: Block Island (the Town of New Shoreham) is reached by ferry or air, so materials, labor and scheduling need their own line items and contingency.
- Insurance: builder's risk and flood coverage can be significant on coastal sites. Get quotes early and include them in carrying costs.
- Schedule risk: seasonal access, weather and contractor availability on the coast can stretch timelines, so build extra months of interest into the plan.
Whether a particular coastal project qualifies depends on the lender, the property and the borrower.
Bristol County: Financing High-Value Coastal Residential Projects
Bristol County is a compact, high-value coastal housing market. Because the county is small, a project's valuation often rests on a limited set of truly comparable sales.
New Construction Loans in Barrington, Bristol and Warren
- Comparable sales: choose recent sales of similar new or fully renovated homes in the same town and neighborhood. A home in Barrington and one in Warren may not be valid comps for each other.
- Budget and contingency: include a contingency suited to the scope; lenders treat a budget with no cushion as a risk.
- Exit strategy: explain how you plan to repay, whether by sale or refinance, and what happens if the sale takes longer than expected.
- Equity: show your cash in the deal and reserves for interest and holding costs.
No lender can guarantee resale values, appreciation or profit. A conservative plan helps the project hold up if the market slows.
Providence County: Financing Urban and Suburban Construction
Providence County has the most transaction volume in the state, but it is not one market. The city of Providence and its surrounding towns have different zoning, lot sizes, values and construction economics.
New Construction Loans in East Providence, Cumberland, Smithfield and Pawtucket
- City versus suburb: an infill project in Providence or Pawtucket often involves smaller lots, tighter zoning and neighboring structures. A new single-family home in Cumberland or Smithfield is more likely to involve subdivision lots, site work and utility connections.
- Zoning and permits: confirm what the zoning allows and where permits stand. Each municipality runs its own process.
- Contractor estimates: bids should be detailed and tied to the plans.
- Valuation: support the completed value with sales from the same town and housing type.
- Borrower experience: lenders want to see similar projects you have completed.
A4 lends on business-purpose residential projects, so confirm that your project type fits before you build a plan around it.
Kent County: Financing Suburban Construction and Rental Investment Projects
Kent County is a secondary market in A4's strategy, centered on suburban construction, renovation and single-family rental investors.
New Construction Loans in East Greenwich, Warwick, West Warwick and Coventry
For a build-to-rent home in Warwick or a spec home in East Greenwich, the exit drives the loan. If you plan to refinance into a long-term rental loan, the expected rent and the refinance terms available at completion matter as much as the build budget. If you plan to sell, comparable sales in the same town matter most. In both cases, lenders review your equity, budget, valuation and experience.
New Construction Loan Requirements in Rhode Island
Most lenders review the same core factors:
- Credit profile and overall financial strength.
- Equity in the project and liquid reserves.
- Land ownership or a purchase contract, and the land cost.
- Plans, permit status and project feasibility.
- Detailed contractor bids and a line-item budget.
- An appraisal or valuation of the completed property.
- Borrower and contractor experience.
- A realistic repayment or exit strategy.
A4 Capital Partners publishes loan sizes from $500K, rates from 8.5% and leverage of up to 85% of total project cost, all subject to underwriting. A4 generally looks for borrowers who have completed projects in the past 24 months. Requirements vary by lender, program, property and borrower.
Construction Loan Costs, Draw Schedules and Funding Requirements
- Interest and fees: compare the rate together with points, origination and draw fees.
- Third-party costs: appraisal, inspections, title, legal and closing expenses.
- Contingency: a reserve for cost overruns and surprises.
- Staged funding: you usually pay for each phase before the draw reimburses it, so plan your cash flow.
- Interest during construction: many construction loans are interest-only, with payments due during the build.
- Completion risk: delays add interest, taxes, insurance and can push the project past the loan maturity.
Hypothetical example: an investor owns a lot and plans a spec home with a line-item construction budget. The lender reviews the plans, the budget, the contractor and comparable sales, then sets a draw schedule. The investor pays for framing, submits a draw, and the lender inspects and releases funds for that line. Numbers and terms in a real deal depend on underwriting.
How to Choose the Right Construction Financing for Your Rhode Island Project
- Location and use: a Jamestown waterfront spec home and a Coventry rental build need different lender strengths.
- Total project cost: make sure the project fits the lender's loan-size range.
- Land ownership: know whether the lender will fund the land, construction or both.
- Equity: confirm how much cash you need at closing and during the build.
- Timeline: the loan term should cover the build, plus time to sell or refinance.
- Funding process: ask how draws, inspections and timing work.
- Project risks: coastal approvals, island logistics and cost overruns.
- Exit strategy: have a primary plan and a backup.
How to Apply for a New Construction Loan in Rhode Island
- Define the project scope and intended property use.
- Prepare land information and ownership documents.
- Obtain architectural plans, permits and contractor estimates as applicable.
- Prepare a detailed construction budget with contingency.
- Gather financial and borrower-experience documentation.
- Discuss financing options with a suitable lender.
- Review the proposed terms, draw schedule, fees and repayment obligations.
- Proceed only after required approvals and closing conditions are satisfied.
Frequently Asked Questions About New Construction Loans in Rhode Island
What is a new construction loan in Rhode Island?
It is short-term financing for building a home, usually released in stages as work is completed and repaid by sale or refinance. A4 offers these loans for business-purpose investment projects.
How do I qualify for a new construction loan in Rhode Island?
Lenders review your credit, equity, reserves, experience, plans, budget, the completed value and your exit plan. Requirements vary by lender and project.
Can I finance land acquisition and construction together?
Some lenders finance part of the land purchase together with construction; others require you to own the land. It depends on the lender and the deal.
Can real estate investors obtain private construction financing?
Yes. Private and balance-sheet lenders, including A4 Capital Partners, finance investment construction projects, subject to underwriting.
How are construction loan funds disbursed?
Usually through draws. After a phase is finished, the lender verifies the work, often by inspection, and releases funds for that part of the budget.
Do construction loans cover luxury and waterfront homes?
They can, but not every property qualifies. Lenders review each site, its approvals, its valuation and the project budget.
What documents are generally needed for a construction loan?
Expect a purchase contract or deed, plans, permit status, an itemized budget, contractor details, a schedule, entity documents, proof of funds, a track record and comparable sales.
Are construction loan requirements different across Rhode Island counties?
Core requirements are similar statewide, but the review differs by site. Coastal approvals, island logistics, zoning and the comparable sales used for valuation vary by town.
Can a construction loan be used for a single-family rental property?
Yes, for eligible investment projects. Lenders will want to see how the loan is repaid, such as a refinance into a long-term rental loan, which is not guaranteed.
How can I discuss construction financing with A4 Capital Partners?
Call +1 203-457-3787, email originations@a4cp.com, or submit your project through the application on this site.
Planning a New Construction Project in Rhode Island?
Whether you're evaluating a luxury coastal home, a suburban residential build or an eligible real estate investment project, understanding your financing options is an important first step. Contact A4 Capital Partners at +1 203-457-3787 or originations@a4cp.com to discuss your project, financing needs and potential lending options.